IDI is a pioneer in the private equity arena in France, with over 50 years of experience in the field and a particular investment focus on SMEs. IDI is one of the first listed investment companies in France (1991), achieving an annualised IRR (dividends reinvested) of 15% over the past 30 years. IDI’s NAV has grown significantly over the years and is now approaching €774.5m (as of June 2026), with an average discount of 30% observed since 2014.
IDI strikes as a private equity firm effectively more aligned to the interests of its stakeholders than the mediocre industry record, in that respect. This is in spite of it resorting to a partnership limited by shares as a legal shell. IDI differs as it has no time constraint and as its management has skin in the game at the holding level as well as at the equity stakes level. Indeed, what sets IDI apart from other private equity players, aside from the fact that most of the investment activity is funded by its own equity capital, is that it operates under a model that is not constrained by time to liquidity that most PE funds are subject to.
On the one hand, this flexible approach allows IDI to accompany the investee companies through the whole development process without having to resort to hasty value-pumping measures in order to appease investors waiting to be paid out. On the other hand, the liberty of not having to adhere to a calendar also allows the company to be agile and seize opportunities when they arise. This may result in IDI exiting investments faster than its more usual investment horizon of five to seven years, to capitalise on favourable market conditions and crystallise higher IRRs.
A resilient flexible investment approach in the face of a crisis
This no-rush approach is conducted by a management team that, all combined, makes up the main shareholder base, with Ancelle et Associés controlling 68.3% of the share capital and 78.2% of voting rights, providing plenty of confidence that the company’s equity capital is being allocated wisely in order to support long-term value creation. The lack of a liquidation schedule also allows IDI to time its exits better in periods of market downturns — as was the case in 2020 at the height of the Coronavirus pandemic — to capitalise on a subsequent recovery in market multiples to crystallise higher rates of return.
Demonstrating the resilience of the IDI model in a volatile market environment, as was the case in the midst of the COVID-19 pandemic, is the performance shown in 2020, posting a 6.11% NAV growth rate. This was mainly led by improved fair values of the Private Equity Europe assets (+€36m) and liquid assets (+€12m), with the former benefitting from improved operational performance and higher valuation multiples at the end of the year, as well as the capital gains on the exit of HEA Expertise, under very favourable valuation conditions agreed before the pandemic, securing a solid 35% IRR. Even after having invested €32m over the course of 2020, IDI closed the year with a €124m-strong total liquidity position (€142m in FY19).
From transformation to capital redeployment
After a resilient 2020 amid adverse market conditions, and a dynamic 2021 with 16 transactions totalling over €300m (+28% NAV growth), IDI delivered another solid performance in 2022 (+12% NAV, 15 deals), which proved to be a landmark year for IDI, as the Group embarked on a bold expansion into third-party asset management. This pivotal decision was marked by the acquisition of Omnes and the establishment of IdiCo, a newly-created entity merging Omnes’ private equity and private debt operations. Through this transformative step, IDI successfully doubled the scale of its third-party asset management business, reaching €1.5bn of AUM. This strategic shift toward a hybrid model, balancing proprietary investments (€25m-€60m, up to €100m in co-investments targeting French and European SMEs) with IdiCo’s smaller, focused investments (€5m-€25m in France), not only expanded IDI’s market reach, but also diversified its revenue streams.
2023 was on a par with the previous years, with an 11% increase in NAV and, above all, a record 21 transactions. The Group’s stand-out deal was the sale of Flex Composite Group to Michelin for an enterprise value of €700m, yielding a 12x return on its initial investment and an IRR of 38%. This transaction significantly boosted IDI’s investment capacity, leaving it with over €300m in available funds.
In essence, whether in tranquil or more dynamic years, IDI enjoys the distinct advantage of choice. After a quieter 2024, investment activity picked up in 2025, with six transactions, including the majority acquisitions of Intersoft Electronics Group and Forsk. The Group also continued to recycle capital in H1 2026, completing the disposal of Winncare while supporting S4BT’s acquisition of HotelHub. These developments reaffirm the strength of IDI’s flexible investment model: the ability to adjust the pace of acquisitions and disposals to market conditions rather than being constrained by a predetermined investment horizon.
IDI: a hands-on shareholder
In the holding company universe, one can distinguish three different types of management styles of the portfolio: firstly, there are those that keep their investments at arms-length and are content with collecting periodic dividends; secondly, are those that get “down and dirty”, getting directly involved in the operations of their investee companies, which can quickly get complicated when new investments fall in completely different sectors.
Then, there is a third path, to which IDI ascribes, a hands-on approach as a shareholder, as it is working in a close relationship with the investee company’s management and getting involved in the supervisory board, but leaving the day-to-day operations to skilled managers who have the valuable knowledge in the respective sectors of activity. This avoids spreading the HoldCo’s resources too thin, which increases the likelihood of execution risks.
Regarding investment strategies, IDI specialises in LBO investments as well as growth capital investments in SMEs. The company’s prudent investment approach extends to the limited leverage maintained at the holding company level, alongside relatively moderate leverage across its portfolio companies. As of December 2025, the portfolio’s average net debt/EBITDA ratio stood at 2.97x, down from 3.41x a year earlier, supported by EBITDA growth and lower net debt at several holdings. This remains well below European LBO market standards, where average leverage reached 4.91x EBITDA in 2025.
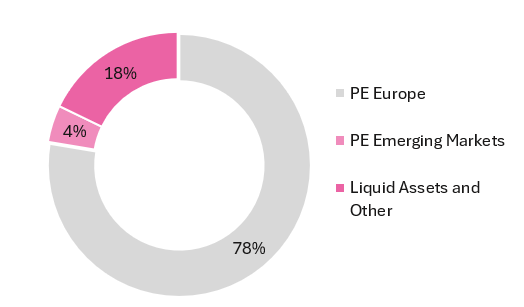
In terms of geographical breakdown, the lion’s share of IDI’s portfolio remains Europe-based, with a strong focus on France. As of December 2025, European private equity accounted for approximately 68% of NAV, against 4% for emerging markets, with liquid assets and other investments representing the remaining 28%. This marks a significant change from December 2023, when liquid assets accounted for 51% of NAV following the disposal of Flex Composite Group. IDI has since progressively redeployed its capital, although its investment capacity remained substantial at €230m as of June 2026, including €35m in undrawn credit facilities.
NAV breakdown as of H1-2026
Concerning the size of the investments, IDI being a relatively smaller player in the private equity space, these range between €10 and €50m and can extend up to €150m with family office type co-investors, i.e. also not time constrained. IDI is flexible in regards to the shareholding size, as its current portfolio includes majority, co-controlled and minority investments, usually determined by the scope of the deal.
An attractive high-growth portfolio
IDI’s portfolio is diversified across a range of sectors, including businesses exposed to structural growth trends such as media services (Dubbing Brothers), digital services (Groupe Positive), education (Talis), and specialised technology (Forsk and Intersoft Electronics Group). The portfolio has continued to evolve, with recent investments strengthening its exposure to niche technology and business services, while the disposal of Winncare in H1 2026 illustrates the ongoing rotation of assets.